
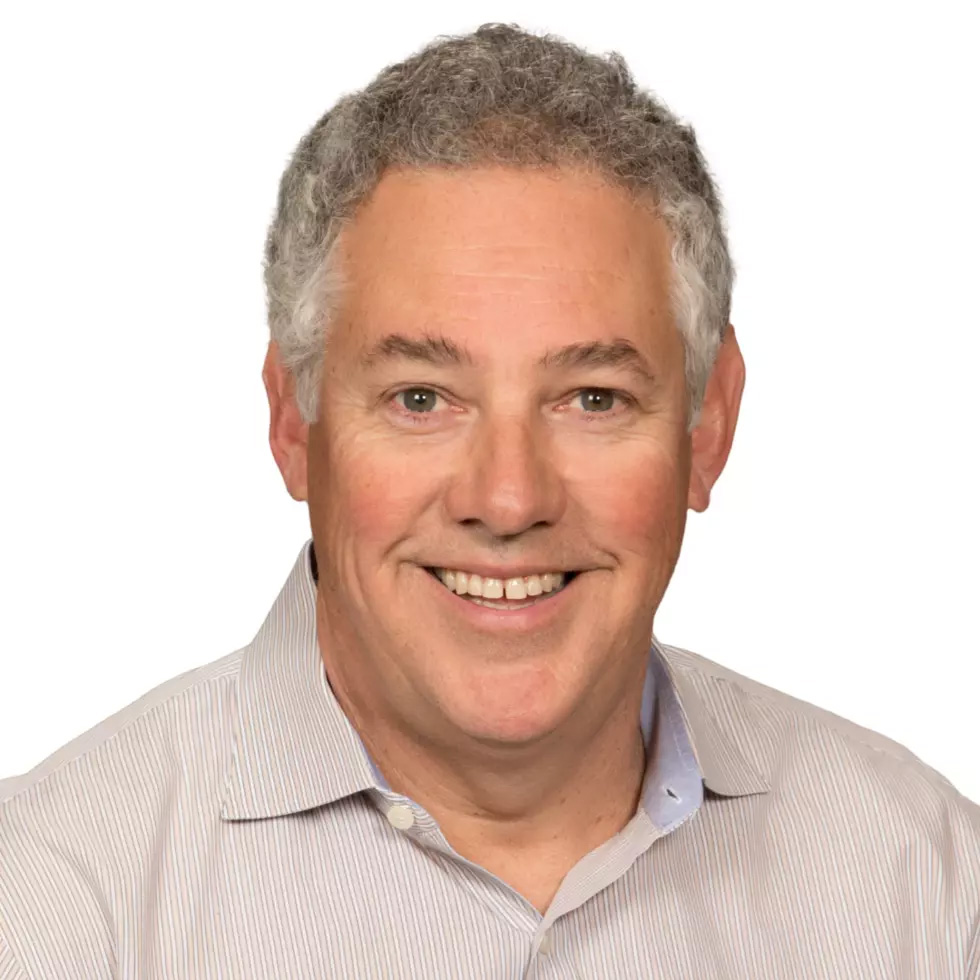

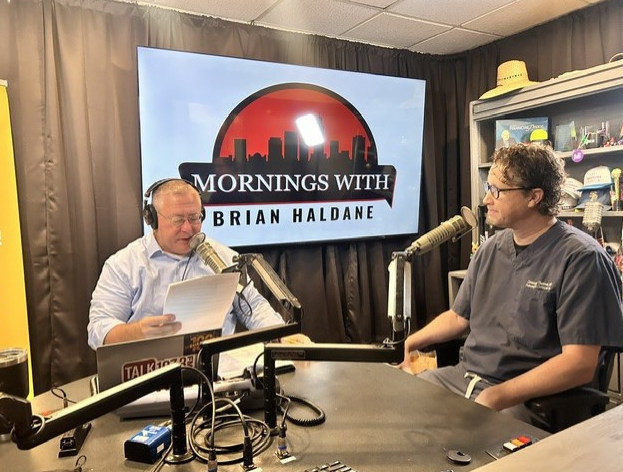

Louisiana Insurance Commissioner Tim Temple provided key updates on the state’s evolving insurance landscape — highlighting significant auto insurance rate reductions, the return of the fortified roof grant program, and strategies for homeowners to save on premiums.
Auto Insurance Rates See Major Decreases
Temple confirmed that over 20 auto insurers have recently lowered rates, some by as much as 10–20%. While many may assume these reductions are due to recent legislative changes, Temple clarified they are mostly the result of market conditions — notably, fewer accidents leading to fewer claims.
“Fewer cars on the road means fewer accidents, which means fewer claims — and that brings premiums down,” Temple said.
He credited free-market dynamics and regulatory flexibility as factors enabling insurers to adjust rates more quickly. A recent change allows insurers to revise rates more than once per year, increasing competition and responsiveness.
Legislation’s Long-Term Promise
Although the latest rate cuts aren’t directly tied to 2024 legislation, Temple remains optimistic that newly passed reforms — like the two-year prescription on auto claims and efforts to curb frivolous litigation — will eventually lower premiums even further.
He’s already begun urging insurers to pass on anticipated savings, saying, “I’ve engaged in conversations with companies, asking them to hedge a bit — start giving Louisianans some premium relief now.”
Fortified Roof Program Reopens
On the homeowners’ side, Temple announced the latest round of the Fortified Roof Program, which provides up to $10,000 in grants to upgrade to storm-resistant roofing. The current application window runs through September 12 at 5:00 PM.
In a welcomed move, those who applied in previous rounds will automatically be entered into this drawing. A separate $10,000 state tax deduction is also available for homeowners who upgrade on their own, although that program is capped at $1 million in total credits.
Wind Mitigation: A Hidden Savings Tool
Temple also encouraged homeowners to invest in a wind mitigation survey, which evaluates a home’s structural resilience. The upfront cost (around $300) can lead to substantial insurance discounts. He shared an example of a New Orleans homeowner saving $2,800 annually just by documenting existing building features.
“It’s an easy win for many,” Temple said, noting that better enforcement of building codes across parishes could eventually reduce the need for these surveys altogether.
Shop Around and Save
As a final note, Temple emphasized the power of shopping for insurance. “It’s a competitive business,” he said. “Companies know they have to offer you a better deal to win your business.”
He encouraged consumers to speak with independent agents and get multiple quotes — a move that has saved some Louisiana residents up to 50% on their premiums.
Bottom Line: Whether you’re behind the wheel or under your roof, there are new and ongoing opportunities to lower insurance costs in Louisiana. With regulatory reforms, incentive programs, and smarter shopping, the insurance landscape in the state is shifting — and consumers are starting to feel the difference.
For more information on programs and resources, visit the Louisiana Department of Insurance website.